Claiming Tax Refunds from HMRC

The tax experts at Spicer & Co Chartered Accountants regularly help sole traders, contractors and businesses to reclaim tax they have overpaid. Often, clients don’t realise they could have reduced their tax liability.

Tax refunds go beyond people who have paid too much tax through a payroll process. There are several reasons why a self-employed person or business may end up paying too much tax.
Taxes - word against Union Jack flag


Why you may be entitled to a tax refund

  • Overestimating your payments on account

If you complete a Self Assessment tax return, HMRC may ask you to make payments on account towards the next year’s tax bill. These are based on your previous year’s income. If your income later drops, you may have paid more than you actually owe, which can result in a refund.

  • Missing allowable business expenses

Many business owners fail to claim all of the expenses they’re entitled to. This could include:

– Office costs or working from home expenses

– Business travel and mileage

– Equipment, software, or tools

– Professional fees and insurance

– Training related to your business

If these costs aren’t included correctly, your tax bill may be higher than it should be. This is frequently spotted by the eagle-eyed tax team at Spicer & Co Chartered Accountants.

3. Capital allowances on equipment

If you purchase equipment such as laptops, machinery or vehicles for business use, you may be able to claim capital allowances. These deductions can significantly reduce your tax bill and may even create a refund.

4. Amendments to previous tax returns
If an error is found after submitting a return, it may be possible to amend the return and claim back tax that was overpaid. In most cases, you can amend Self Assessment tax returns for up to four years after the end of the relevant tax year.

Steps to claiming a tax refund from HMRC

red laptop

1. Check if you’re owed a tax refund

The government’s online tax refund tool enables you to check if you’ve paid too much tax.

2. Request the refund online

If a refund is due, you can request payment through your HMRC online account. Refunds are usually paid directly into your bank account.

3. Reduce payments on account

If your income has dropped, you may also be able to apply to reduce your payments on account to prevent overpaying tax in the first place.

footstep changing direction

Alternatively, work with your accountant to ensure your tax returns are accurate. If you are owed a refund, they can liaise with HMRC, managing the process on your behalf and cutting through the jargon.

A tax tip for business owners

‘Keeping accurate records throughout the year is one of the best ways to avoid overpaying tax,’ says Max, an accountant at Spicer & Co. ‘Make sure you keep receipts, track expenses and review your accounts regularly. Paying the right amount of tax helps your cash flow too.’

How we can help you

Do you think you’ve paid too much tax?

Do you want to make sure you are claiming everything you and/or your business are entitled to?

For many self-employed people and companies, a quick review of their accounts can uncover legitimate tax savings or refunds that might otherwise go unclaimed.

Talk to the tax experts at Spicer & Co Chartered Accountants in Dunstable. Let’s ensure you only pay the tax that’s actually due and avoid the need for a tax refund.
Spring Statement Summary

Rachel Reeves’ Spring Statement didn’t arrive with the fanfare of anticipation that accompanied the Autumn Budget. This low-key announcement was made today (3 March 2026).

Overshadowed by events in the Middle East and not reflecting their imminent impact on inflation and energy costs, here are the key announcements:

How is the economy doing?

  • Anticipated economic growth of 1.1% is forecast for this year, increasing to 1.6% in both 2027 and 2028 and 1.5% in both 2029 and 2030.
  • Inflation is set to reach its forecast level of 2% by the end of this year.
  • Unemployment is expected to rise to 5.3% this year. This is higher than the Autumn Budget forecast of 4.9%. It’s expected to fall gradually, decreasing to 4.1% by 2030.
  • In 2025-26, Real Household Disposable Income per person is expected to grow by 0.1% and then average 0.5% growth a year until 2029.
person lookimg through magnifying glass

What’s happening next?

  • The anticipated relief for business rates and student loans did not materialise.
  • No new tax rises were announced. The government’s total tax take is forecast to hit a “historic high” by 2030-31, rising to almost 43% of GDP. That’s an increase from around 39% of GDP in 2024-25.
  • The two-child benefit cap will be removed from April 2026, and welfare benefits will rise in line with inflation.
  • The introduction of increases to National Insurance and the National Living Wage, together with the new Employment Rights Act, has dampened recruitment and investment.
  • The roll-out of Making Tax Digital for Income Tax continues as planned, starting in April 2026 for sole traders and landlords with qualifying income of over £50,000. (Read more)

Effectively, this Spring Statement is seen as a holding exercise with more significant changes needed in the next Autumn Budget. Full details of the Spring Forecast 2026 are available online.

‘The Chancellor kept her promise of keeping to one major fiscal event each year to offer stability and certainty on upcoming tax and spending changes,’ says Suzanne Spicer of Spicer & Co Chartered Accountants in Dunstable. ‘There’s little significant change affecting people and businesses on a day-to-day basis. We anticipate bigger announcements in the autumn.’

The Autumn Budget is planned for 26 November 2026.

How we can help you

If you are an employer grappling with the recent changes to National Insurance and National Living Wage, our friendly payroll experts are here to help.

If you are a sole trader or landlord needing to comply with Making Tax Digital for Income Tax, we’re here to help.

Please contact us for an initial discussion without obligation.

The Sole Trader to Limited Company Transition

Changing from a sole trader to a limited company involves moving from being personally identical to your business to creating a separate legal entity. This process provides limited liability protection for your personal assets but introduces stricter administrative and tax obligations.

Limited liability and perceived business credibility are the main reasons that people choose to form a limited company rather than operate as a sole trader. (However, just one person is needed to create a limited company.) Different tax rules apply, with the limited company paying its own corporation tax while the director and shareholder(s) pay income tax.

With Making Tax Digital for Income Tax going live on 6 April 2026, people with over £50,000 of qualifying income may find that becoming a limited company rather than a sole trader offers greater tax efficiency. It would exempt you from MTD IT; however, more costly and time-consuming administration would be involved …

The word 'Tax'

What’s involved with transitioning to a limited company?

1. Check that this change is beneficial to you. Talk to an accountant to ensure moving to this new, more formal business structure will help you operationally and financially. Assuming you continue with your business transition …

2. Register your new limited company

  • Choose a name: This must be unique and end in “Limited” or “Ltd”. Use the Companies House Name Availability Checker to see if your chosen name is available. Before going ahead, it’s wise to see if the website domain name is also available. All the online website services have domain checking tools.
  • Appoint roles: You must have at least one director (to run the company) and one shareholder (to own it). One person can be appointed to both roles (read more). Every person with significant control should be recorded at Companies House.
  • Submit documents: You need a Memorandum of Association (agreement to form the company) and Articles of Association (rules for running it).
  • Register: Online registration via Companies House costs £100.
Settings Wheel

3. Inform HMRC

  • Deregister as self-employed:Inform HMRC you are stopping sole trader operations.
  • Register for corporation tax:This must be done within three months of starting to trade as a limited company.
  • Final tax return:You must file a final Self Assessment tax return for your period as a sole trader. (Note: If you are an employee and/or shareholder of your new limited company, you may still need to complete a tax return.)

4. Financial requirements

  • Transfer of business assets: this involves creating a valued inventory of all assets such as stock, equipment and intellectual property. The valuation must reflect fair market value. Assets are typically “sold” to the company or transferred in exchange for shares (which may qualify for Incorporation Relief to defer Capital Gains Tax).
  • Business bank account:A new account must be opened in the company’s name. You cannot continue using your personal or sole trader account as the company is a separate entity.

All contracts and contacts (customers, suppliers, and stakeholders) must be updated to reflect your new legal status and payment details.

person lookimg through magnifying glass

5. Ongoing responsibilities

  • Once your limited company has started trading, a range of company and accounting requirements exists. The government’s website details your responsibilities when operating a limited company.

Legally, you don’t need to involve an accountant as you switch from being a sole trader to a limited company. However, using professional support saves valuable time and avoids costly mistakes as well as the stress involved with the registration process.

How we can help

The friendly experts at Spicer & Co Chartered Accountants in Dunstable can help you by:

  • assessing whether it’s the right financial move for you,
  • helping with the incorporation process,
  • ensuring you transfer assets correctly, and
  • managing your tax and filing requirements.
Change Sign

‘As well as offering business consultancy, we can offer advice to ensure you are as tax-efficient as possible,’ says Max of Spicer & Co. ‘Maybe you are affected by Making Tax Digital for Income Tax? If so, we can  review whether there are tax advantages to be gained by transitioning from a sole trader to a limited company.’

To find out more, arrange an initial call without obligation. Let’s explore the options and determine the best business structure for you.

What Landlords Need to Know About Making Tax Digital

Do you own a rental or holiday property?

Landlords earning income over £50,000 either solely through rental income or from a combination of rental and self employed income must get ready for Making Tax Digital for Income Tax. Does this apply to you?

It starts from 6 April 2026. Importantly, Making Tax Digital (MTD) involves quarterly returns. Your first return covers the period 6 April – 7 July 2026, with a submission deadline of 7 August 2026. Making Tax Digital just got real!

If you earn less than £50,000 but more than £30,000 a year, you’ll be required to comply with MTD for Income Tax next year, from 6 April 2027. Landlords earning rental and/or self employed income over £20,000 and less than £30,000 will need to implement MTD practices from 6 April 2028.

Key 453500_640

Preparing for Making Tax Digital

Step 1 – Does it apply to you?

If you’re unsure of whether you need to adopt MTD for Income Tax, you can visit the government’s website for more information and use the online MTD tool.

Step 2 – Understand the requirements

The fundamental requirement of MTD is keeping digital records. This enables you to submit quarterly updates to HMRC and complete a Self Assessment tax return using software that’s compatible with MTD. The quarterly submissions are more frequent than the current annual return requirement and you still need to submit a tax return each year.

Step 3 – Choosing your software

There’s a useful online tool to help you search for software that works with MTD for Income Tax. The Spicer & Co team works with all the main online bookkeeping software packages. However we recommend Xero for its instant updates, flexibility and ease of access. Going paperless is environmentally friendly too.

Step 4 – Go digital

Why wait until the last minute before keeping your financial records digitally? If you are not already running a paperless bookkeeping system for your property rental business, start now. Get to know your new software package without the stress of a looming deadline.

Step 5 – Consider professional accountancy support

Talking to an accountant with specialist property accounting knowledge will help you to minimise your tax as well as comply with MTD. We can also review your business structure to determine if your current format offers you the best opportunities to minimise your tax liability.

Red wireless mouse for computer

How we can help you

The Spicer & Co can help you navigate the requirements of MTD, from helping you to set up MTD-compliant software to submitting information to HMRC when needed. As well as ensuring your property income complies with MTD, we can ensure you are operating as tax efficiently as possible. Contact us for an initial discussion without obligation. Property and tax are two of our favourite topics!

How Green Choices Can Lower Tax

Sustainable choices demonstrate that your business is environmentally friendly, attracting both customers and employees. Being environmentally proactive can also be financially smart for your business. Here’s how conscious “green” choices are beneficial from a tax perspective:

Annual Investment Allowance (AIA)
If you invest in qualifying energy-efficient equipment, you may be able to deduct 100% of the cost from your profits using the Annual Investment Allowance. This means a greener upgrade could reduce your corporation tax bill.

Electric Vehicles & Low-Emission Cars
Are you switching your fleet to electric? Your business can claim 100% First-Year Allowances (FYA) on new electric cars and vans, and cars and vans with zero CO₂ emissions. You can also claim corporation tax relief on the installation of electric charging points.

In addition, electric vehicles often have lower running costs and reduced Class 1A NIC due to lower Benefit-in-Kind (BiK) rates.

Electric Car charging

Capital Allowances on Energy-Saving Investments
Certain energy-efficient technologies qualify for enhanced capital allowances. This means you can allocate the full cost against profit in the year of purchase. Examples of allowable technologies are:

  • low-energy lighting
  • solar panels
  • heat pumps
  • efficient heating and cooling systems

It’s best to check the eligibility of your intended purchase prior to buying the equipment.

R&D Tax Relief for Green Innovation
If your business is developing new eco-friendly products, processes or services, you may be eligible for Research & Development (R&D) tax relief. This can offer a significant reduction in your tax bill or even a cash credit.

Reduced Running Costs
Going green often leads to:

  • operational savings,
  • lower utility bills, and
  • reduced waste disposal costs.
Idea

If you’d like to explore which green investments save the most tax for your business, we’re here to help. Talk to the friendly experts at Spicer & Co Chartered Accountants. We’re keen to help you make environmentally friendly decisions that protect your profit as well as the planet.

Tax Planning: What To Do Now

The November 2025 Budget introduced a number of changes affecting taxpayers. They are to be introduced during the next few years, starting from April 2026. Good tax planning now can make a big difference later. The key changes are below, along with the actions to take now, making the most of current tax planning opportunities.

1. Making Tax Digital for Income Tax

In April 2026, MTD for Income Tax starts for sole traders and landlords with self employed income over £50,000. (Explore further stages of MTD for Income Tax). Now is the time to ensure you’re using compliant bookkeeping and reporting systems, avoiding potential penalties and stress.

2. Tax on Dividends

Dividend tax rates are set to increase by 2% from April 2026, making dividend-based remuneration slightly less attractive for limited company owners. This is a good time to review your balance of salary, dividends and pension contributions.

Mark 804936_640

3. ISA Savings

ISA rules are changing. The overall personal threshold remains at £20,000 each year, however, from April 2027 only up to £12,000 can be invested in cash ISAs (for people aged under 65). To make the most of the full allowance, part of your annual allowance must be invested rather than held in cash ISA accounts. While ISAs remain one of the most generous tax shelters available, you should review how you place your ISA allocation. If you prefer cash ISAs, ensure you make the most of the last £20,000 cash limit in 2026/27.

4. Owners of Large Properties

Owners of high-value residential property should be aware of a new annual property surcharge on homes valued above £2 million. The new “mansion tax” starts at £2,500 per year, rising to £7,500 annual fee for properties worth more than £5 million. It applies from April 2028. This may influence decisions about ownership structures, succession planning or the timing of sales. Now is a good time to review your property plans.

House key

5. Pension Salary Sacrifice Changes

A major change for higher earners is the introduction of a cap on National Insurance relief for salary sacrifice pension contributions. From April 2029, contributions above £2,000 will no longer benefit from NI savings. For many people, this makes the next three years an opportunity to maximise pension funding while reliefs are still generous.

6. Frozen Income Tax Thresholds

National Insurance and income tax thresholds are to remain frozen until 5 April 2031. This means that, as wages rise, more people will drift into higher tax bands. This “fiscal drag” makes pension contributions, gift aid and careful income timing valuable tax planning tools.

‘The key message from these changes is timing,’ says Anna, Accounts and Operations Manager at Spicer & Co Chartered Accountants in Dunstable. ‘Many significant changes are still ahead, which means there is a real opportunity to plan proactively. A review now could save a meaningful amount of tax over the coming years.’

Would you like to minimise your tax liability?

Enjoy a free initial discussion without jargon, just friendly, practical tips. Talk to the tax experts at Spicer & Co. Why pay more than you need to?

two people in a business meeting

A Fun Review of 2025

As the festive break is almost here! 2025 has been hectic and enjoyable. Here’s a snapshot of our year…

Jan 
Our team worked hard to complete a huge number of tax returns!
Digital platforms such as eBay began mandatory reporting of seller data to HMRC.

Get Kids Going Charity EventFeb
Business rates relief of 40% for film studios was introduced – very relevant for the growing film industry in Herts and Beds.

March
We enjoyed a delicious afternoon tea for the charity Get Kids Going.

Congratulations to Barry from Homefix (pictured with Suzanne), who won a cake by guessing its weight!


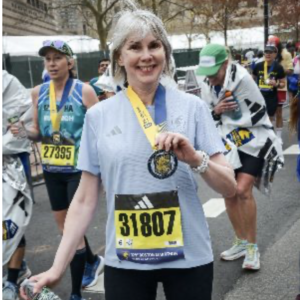
Suzanne of Spoicer & Co finsihing the Boston MarathonApril 
Suzanne completed the Boston Marathon. She is now a Six Star Finisher, having completed all the original six major marathons worldwide. Wow!

Income from Furnished Holiday Lets is now treated the same as other property income.

May 
HMRC’s late payment interest rate decreased to 8.25% and the repayment interest rate to 3.25%. However, it’s best to plan your tax payments and avoid any penalties!

June
Huge congratulations to Annie on her wedding. We wish you every happiness together.


Roby from Spicer & CoJuly 
Suzanne was a panellist for Side Hustle Lab: Finance & Growing Sustainably, alongside Small Business Britain and eBay.

August
HMRC confirmed it is proceeding with MTD for Income Tax Self Assessment (ITSA), set to start in April 2026 for those with qualifying income over £50,000 in the 2024/25 tax year.

September
Ruby (pictured) joined the Spicer & Co team as our new apprentice. Welcome Ruby!

Spicer & Co became a finalist in The Great British Business & Community Awards in two categories.


Spicer & Co team at Luton RunFestOctober
We won silver recognition in two categories at Best Business Women Awards.
The Spicer & Co team joined the Luton RunFest.

November
Identification verification became compulsory for key people involved with limited companies.
Our team advised clients affected by the Autumn Budget announcements.

Spicer & Co TreeDecember
Merry Christmas from everyone at Spicer & Co.
Our last working day before Christmas is 24 Dec (we close at 1pm). We’re back to work on 2 Jan. See you in 2026!

We hope you have a lovely Christmas and a happy, successful New Year.


Cash Flow Management Tips

Cash flow is the lifeblood of any small business and one of the biggest challenges for business owners. Timing is everything! Even profitable businesses can face difficulties if they don’t proactively manage their cash flow.

A recent survey shows that 62% of UK small businesses are owed money from unpaid invoices. The research showed that a higher volume of overdue invoices increases cash reserve spending and credit use, along with delayed business investment and growth. (Intuit QuickBooks)

‘It’s amazing how quickly cash flow problems spread throughout the business. Ultimately, they can create problems in order completion and employee retention as well as being able to pay the business’s bills,’ says Shivani of Spicer & Co, Chartered Accountants in Dunstable. ‘It’s best to be proactive, taking preventive action to minimise cash flow issues.’

Seven tips for good cashflow management

1. Understand your cash flow cycle. When do customers usually pay you? When are your major expenses—rent, wages, VAT, suppliers—due? Once you comprehend the timing, you’ll be better prepared to anticipate problems and prevent surprises.

Paid 1726356_640

2. Keep your bookkeeping up to date. Accurate, timely bookkeeping is essential. Using cloud accounting software such as Xero can make this painless, showing your cash position in real time.

3. Review payment terms. Consider shortening payment terms, setting up automated invoice reminders, or offering small discounts for early payment. If you invoice regularly, a direct debit service can significantly improve payment reliability.

4. Build a cash reserve. Setting aside even a small portion of monthly turnover can create a buffer for quieter periods. Navigate slow business times with confidence by keeping three months of operating expenses in reserve. This safeguard offers valuable peace of mind.

5. Review your costs. Analysing your expenses shows where savings can be made. Are there subscriptions you no longer use? Can you renegotiate contracts with suppliers? Small, consistent savings can significantly improve cash flow.

6. Plan for tax obligations. Set aside money for tax payments such as corporation tax, VAT or income tax. Keeping these funds separate helps avoid missed payment deadlines and late payment penalties.

Red piggy bank for saving money

7. Seek advice early. If you’re unsure about cashflow forecasts or find it hard to maintain consistency, let us know. An early chat and timely business advice can often prevent future issues.

Business resilience via proactive cash flow

Strong cashflow management gives your business resilience. As the owner,  you’ll have the confidence to make informed business decisions to achieve your goals. Your business will still have both excellent and rocky periods, however proactive cash flow and regular monitoring will help you to navigate these periods confidently.

Are you concerned about your cash flow?

Would you like your business to be more resilient?

Talk to the friendly experts at Spicer & Co in Dunstable. Let’s explore the options.

Autumn Budget 2025 Update

Rachel Reeves’ second Autumn Statement was highly anticipated. She announced it today (26 November) ending weeks of speculation.

How does the Autumn Budget impact you or your business? Here’s a handy summary of the key points announced today (26 November).

If you have any queries or concerns, talk to the team at Spicer & Co. We’ll cut through the jargon, offering clear advice … and a coffee.

Personal Tax

  • National Insurance and income tax thresholds are to remain frozen for an additional three years, until 2028.
  • The annual ISA allowance will be kept at £20,000 for stocks and shares ISAs. The annual Cash ISA allowance for people aged under 65 will decrease to £12,000. Savers aged 65 and over can still save up to £20,000pa in cash ISAs.
  • Tax on dividends and savings is to increase by 2% (basic and higher tax rates)
  • A new income tax rate for property tax was announced. From April 2027, the property basic rate will be 22%, the property higher rate will be 42% and the property additional rate will be 47%. Finance cost relief will be provided at the separate property basic rate (22%).
  • A £2,000 cap on salary sacrifice from pensions will apply in 2029.

Business Tax

Business tax thresholds and rates remain unchanged. However, employers will face additional costs due to minimum wage increases (see below).

Support was offered to the retail, hospitality and leisure sectors, introducing permanently lower tax rates for over 750,000 retail, hospitality and leisure properties. Also affecting the leisure sector, English regional mayors to be given powers to tax overnight stays in hotels and holiday lets, echoing existing plans in Scotland and Wales.

Online gambling profits are to be taxed at 40% (now 21%), and the current 10% bingo tax is to be abolished.

Benefits and Wages

  • Many families will welcome the scrapping of the cap limiting households on universal or child tax credit from receiving payments for a third or subsequent child. This is to be implemented in April 2026.
  • National Minimum Wage for 18 to 20 year olds will increase from £10 to £10.85 an hour.
  • Living Wage and National minimum Wage for 21 years old and over will go up from £12.21 to £12.71 an hour.
  • Free apprenticeships are to become available to SMEs.

Property

The anticipated “mansion tax” was confirmed. This will be an annual £2,500 charge for properties worth more than £2m, rising to a £7,500 for properties worth more than £5m. This move involves revaluing homes in bands F, G, and H. The surcharge will be collected alongside council tax.

Transport

  • A range of announcements affected travellers. Rail fares are to be frozen for the next year and fuel duty remains the same until September 2026.
  • A new tax for electric vehicles and plug-hybrid cars is to be introduced in 2028.
  • The Motability scheme enables people claiming particular disability benefits to lease vehicles more cheaply. Premium vehicles are to be excluded from the scheme.

Additional News

The Chancellor stated her intention to tackle Construction Industry Scheme fraud and promoters of tax avoidance. She also confirmed the anticipated expansion of the sugar levy to milk products (such as lattes and milkshakes) from 2028.

What Landlords Can and Can’t Claim

The tax rules that apply to property rental income are complex, with many changes in recent years. At Spicer & Co Chartered Accountants in Dunstable, we specialise in helping property investors understand the requirements involved.

“Which expenses can I claim against my rental income?”‘ says Max, an accountant with Spicer & Co. ‘Understanding this can make a big difference to your tax bill and ensures you stay fully compliant with HMRC.’

Are you a property landlord?

Here’s a straightforward guide to what landlords can and cannot claim.

model of house with key

The Expenses Landlords CAN Claim

HMRC allows landlords to deduct expenses that are “wholly and exclusively” for renting out the property.

Common allowable expenses include:

  • Repairs and maintenance – fixing leaks, broken fixtures, or redecorating.
  • Letting agent and management fees – including tenant-finding services and rent collection.
  • Accountancy fees – for preparing rental accounts and tax returns.
  • Landlord insurance premiums – buildings, contents, and rent guarantee policies.
  • Utility bills and council tax – if you pay these for tenants.
  • Service charges and ground rent – for leasehold or managed properties.
  • Travel costs – mileage or actual travel costs for property visits (45p per mile is HMRC’s current rate).
  • Replacement of domestic items – furniture, white goods, or kitchenware in furnished lets (replacement only, not upgrades).

A comprehensive list of allowable expenses can be seen at GOV.UK.

Does your property qualify as a furnished holiday let (FHL)? If it meets these criteria, the answer is “yes”:

  • Your rental property is available for short-term letting to the public for 210 days and actually let for 105 days or more in each tax year, and
  • It is not used as a long-term let of over 31 days for significant periods.

Owners of FHLs can still:

  • Deduct full mortgage interest.
  • Claim capital allowances on furniture and equipment.
  • Access certain business reliefs on sale (including 10% CGT rate).

New requirements for FHLs were introduced in 2024. Please contact us if you have any questions.

House 2773196_640

What Landlords CANNOT Claim as Expenses

‘Many landlords are surprised to learn certain expenses are not deductible,’ says Max. ‘Ensuring you only claim for allowable expenses reduces stress and keeps you on the right side of HMRC. If in doubt, please let us know. We’re happy to clarify whether you can or can’t claim for the expense involved.’

Expenses subject to popular misconception but are NOT tax-deductible are:

  • Capital improvements – upgrades, extensions, or high-spec renovations are capital, not repair costs.
  • Property purchase costs – stamp duty, legal fees, and survey costs are capital expenses.
  • Your own labour – time spent managing or maintaining the property personally isn’t allowable.
  • Personal use – any costs relating to periods you or friends/family occupy the property.
  • Mortgage repayments – only the interest element qualifies.
  • Pre-letting costs – initial decoration or furnishing before tenants move in.
  • Fines or penalties – including parking tickets, late tax filings, or tenancy deposit penalties.
Traffic Sign for warning

Making Tax Digital for Landlords

Making Tax Digital (MTD) for Income Tax affects landlords. The first phase starts on 6 April 2026 for self-employed individuals and landlords with qualifying income over £50,000. Other landlords are impacted in further phases – please check the MTD for Income Tax timeline.

Specialist Support for Landlords

Spicer & Co Chartered Accountants in Dunstable specialises in helping property landlords understand what they can claim and how to structure their accounts efficiently.

Contact us for an initial discussion without obligation to see how we can help your rental property stay compliant with maximise tax efficiency.